A big September, in more ways than one
Your Money & Property Update | September 2026
Celebrate Women Expo and Awards - a September highlight
This month I had the privilege of being part of the Celebrate Women Expo and Awards - and I want to take a moment to share what it meant.
On Saturday evening I attended the Awards Gala as a finalist in two categories - Amplifier of Good and Next Voice Rising. I also had the honour of judging & presenting the Mum Who Moves Mountains Award on stage. Recognition often happens quietly, in the background, and this night was a reminder that it matters, for everyone in that room doing the work without always being seen.
Sunday was the Expo, and it was one of those days that fills you up.
I delivered my talk, Money Made Simple, and the room was engaged, curious, and asking all the right questions. A few days later I received messages from women saying the talk made them feel more confident about money for the first time.
That is the impact I want to leave. Every single time.
I spoke to so many incredible women across the day, shared resources, and hopefully planted a few seeds. If you were there - thank you for showing up. And if you want to see more from the day, check out my socials.
Financial literacy is the new abundance. And days like Sunday remind me exactly why.
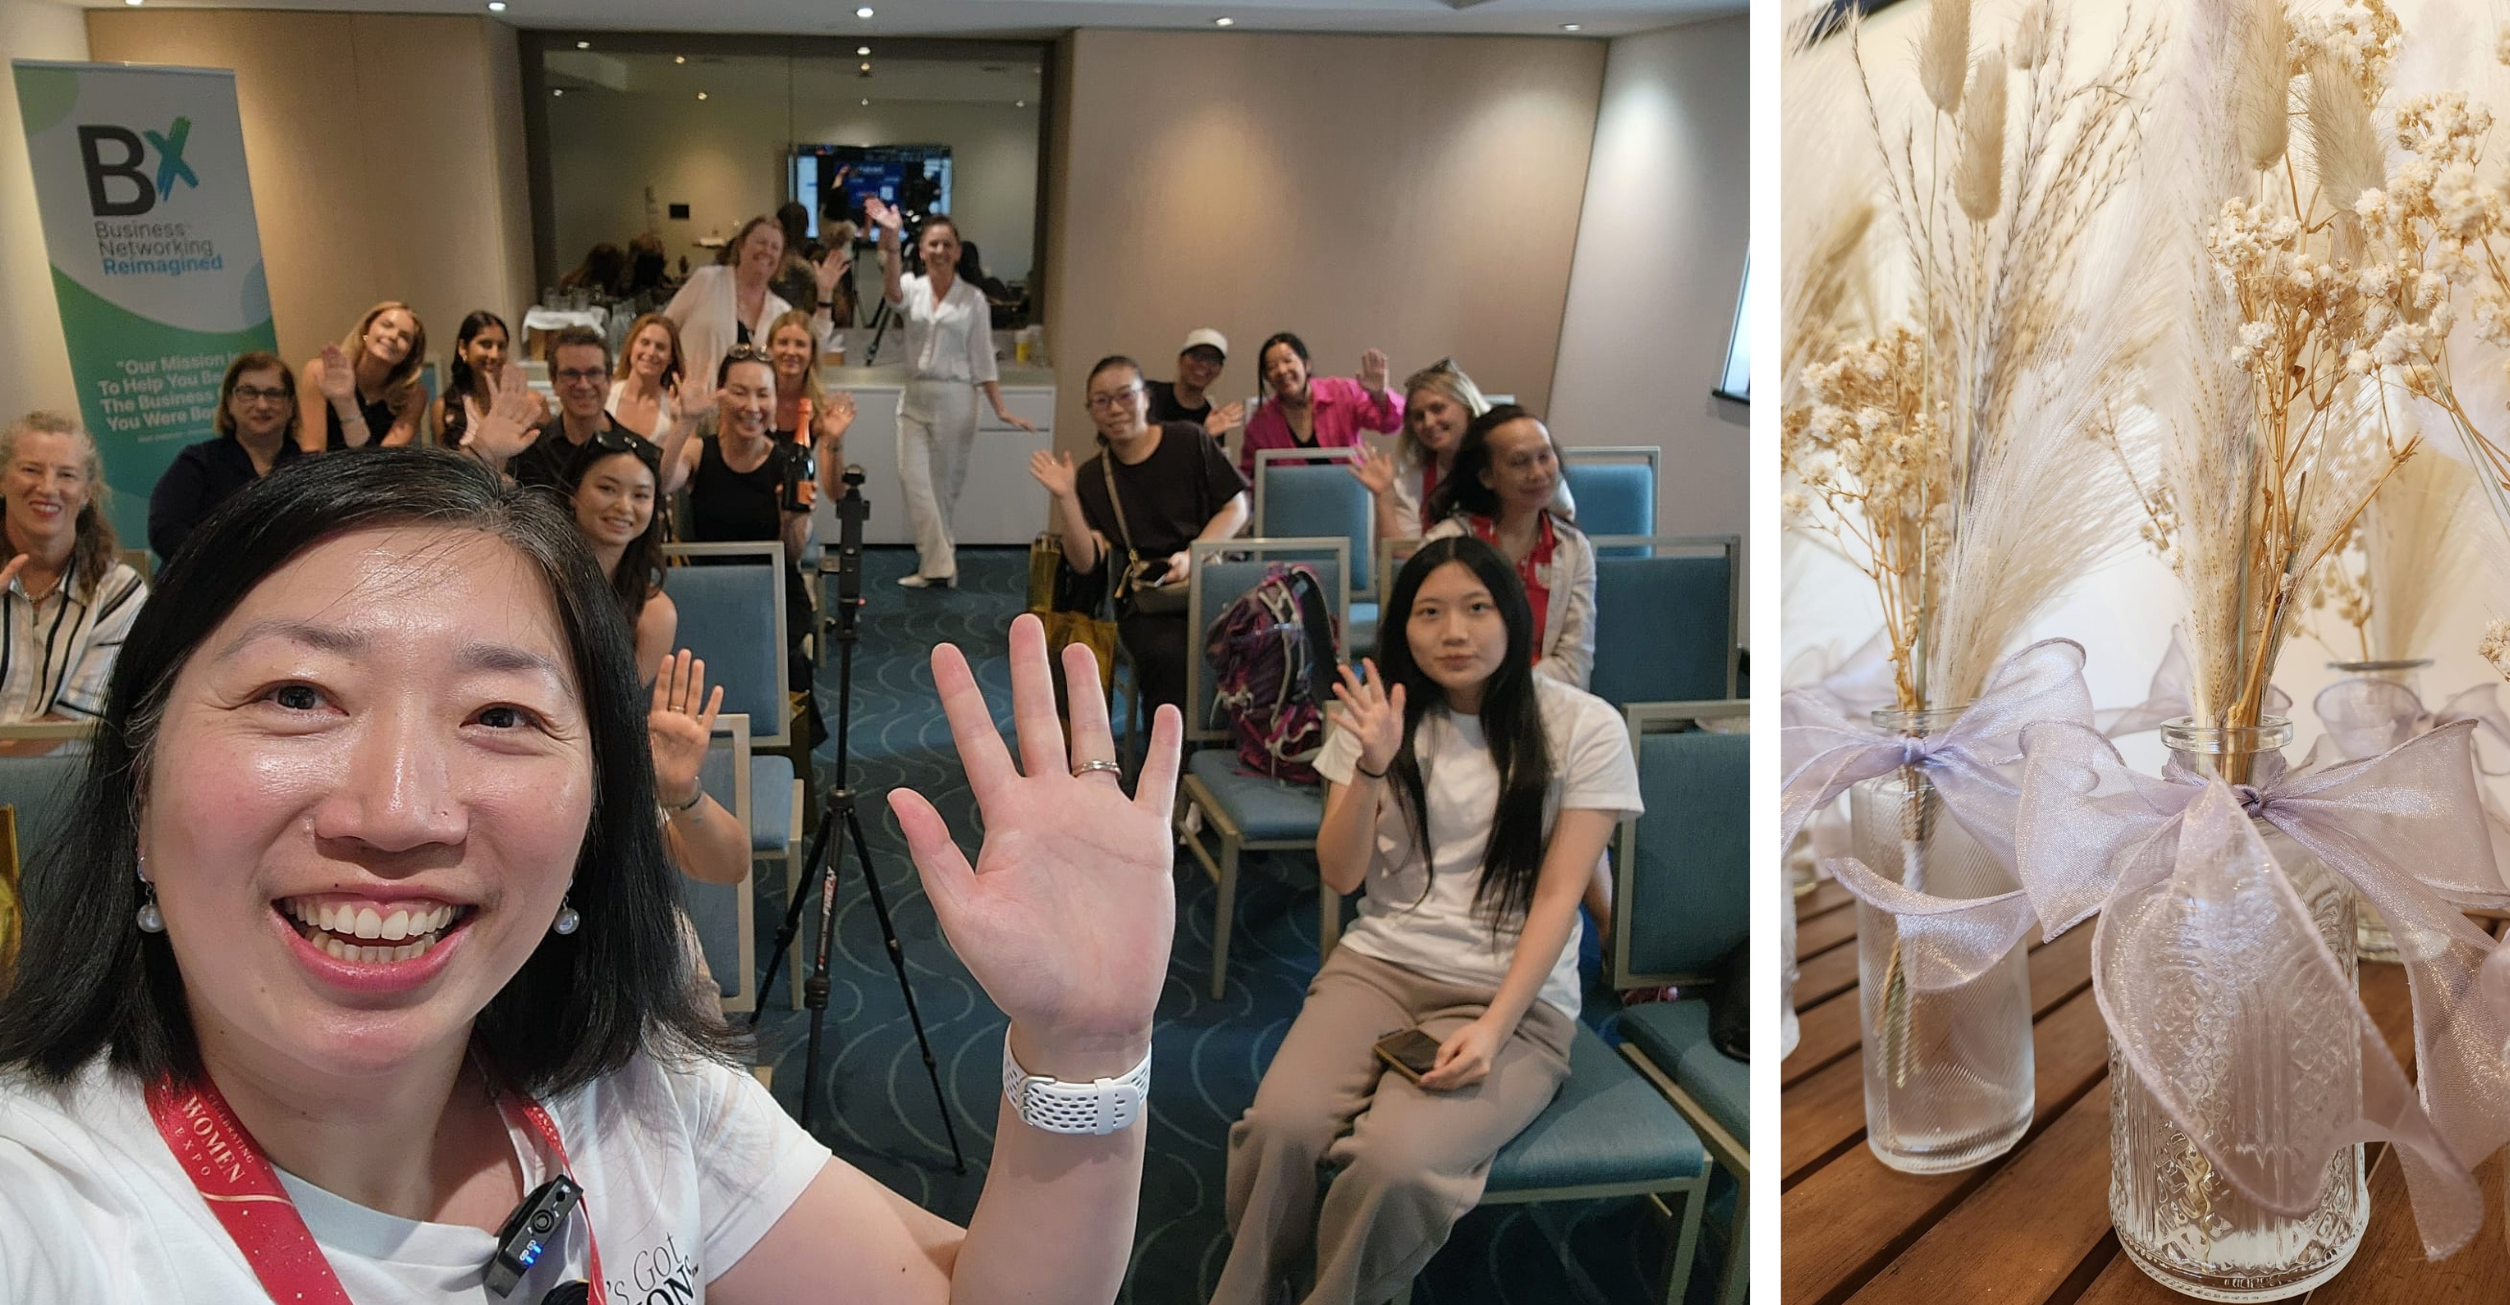
Now, to the money news. And there is a lot of it this month.
RBA - another rate hike is coming
Tomorrow, 29 September, the RBA board meets. And markets are pricing a 92-94% probability of another 25 basis point hike - the highest probability of any meeting this year.
If delivered, the cash rate moves from 4.35% to 4.60%.
All seven major banks are now forecasting a September hike - including CBA and Westpac who shifted their calls forward from November. ANZ is the most hawkish, forecasting hikes in both September and November, which would take the cash rate to 4.85% by year end.
To put this in perspective - we have now had four rate hikes in 2026 alone. Every increase adds to the pressure on household budgets and borrowing capacity.
What this means for you:
A buyer with an average $735,000 mortgage has already seen repayments climb by more than $350 a month since February
Borrowing capacity for a median income household has fallen by 7%, or over $53,000
Another hike tomorrow adds further pressure on both
Fixed rates are already moving - do not wait
Here is something most people do not realise. Banks do not wait for the RBA to move before they act.
Fixed rates have already started rising ahead of tomorrow's expected decision. Lenders are pricing in the hike now - which means if you are considering fixing any part of your loan, the window to act is closing.
This is not advice to fix your entire loan. But it is a prompt to have the conversation. What is your current rate? When did you last review it? Do you know your options?
If you want to talk it through, send me a message.
Inflation - still sticky, still hurting
The July CPI eased slightly to 3.5%, down from 3.8% in June. That sounds like progress - and it is, modestly.
But here is the number that matters more. Trimmed mean inflation - the RBA's preferred measure of underlying inflation - held at 3.6% in July, unchanged from June, and still well above the RBA's 2-3% target band.
That stickiness is exactly why the RBA is moving again tomorrow.
The three areas still hitting Australians hardest:
Housing - up 6.8% annually. Rents up 3.6% year on year. Sydney housing costs up 7.5% annually.
Food and groceries - up 3.3% annually. Every trip to the supermarket confirms this.
Recreation and services - up 3.3% annually. The cost of everyday life is not easing the way people hoped.
The next CPI print lands tomorrow - 30 September - the day after the RBA decision. That data will shape what happens at the November meeting.
Property market - prices are falling and homes are sitting longer
This is now a clear, sustained correction. Not a blip.
National dwelling prices fell 0.9% in August, marking the fifth consecutive month of falls. Sydney prices fell 1.4% for the month and are now 7.1% below their recent peak. Melbourne is down 1.1% for the month and 6.5% below its peak. Brisbane, Perth and Adelaide are also now off their highs.
And homes are sitting on the market much longer.
The median days on market has risen to 38 days - the highest level since October 2022 - up from 29 days a year earlier. That is the 3x to 4x longer selling timeframe you are hearing about and seeing on the ground. It is real, and it is data confirmed.
NAB is forecasting peak to trough declines of approximately 10% in Sydney and Melbourne across 2026.
Buying, selling, or both - timing matters more than ever right now
If you are buying - this market has shifted in your favour. More stock, longer negotiation windows, motivated sellers. For a prepared buyer with clear borrowing capacity, there is genuine opportunity here.
If you are selling - be realistic about timeframes and pricing. The days of a quick weekend sale at above asking are behind us for now. Plan for longer. Price right from the start.
If you are doing both - this is where it gets critical.
Selling and buying in the same market requires careful sequencing. You do not want to sell, find yourself without a property, and watch prices recover while you wait. And you do not want to buy before you have sold and end up carrying two mortgages in a rising rate environment.
Timing is everything. Get advice before you move.
If you are thinking about any of this - send me a message, book a call. Let us talk through your situation before you make a move.
Louise Chiu | Chartered Accountant | Financial Educator | Mortgage Mentor
General information only and does not take into account your personal financial situation or objectives. Please seek advice from a qualified financial adviser, accountant and legal professional before making any financial or property decisions.
